NPK Lowers 2026 Outlook As Dry Texas Weather Idles Mats, Though Adjusted EBITDA Margin Hits 26.2%
The mat maker's third-quarter revenue rose 11%, but free cash flow turned negative and the forecast came down.


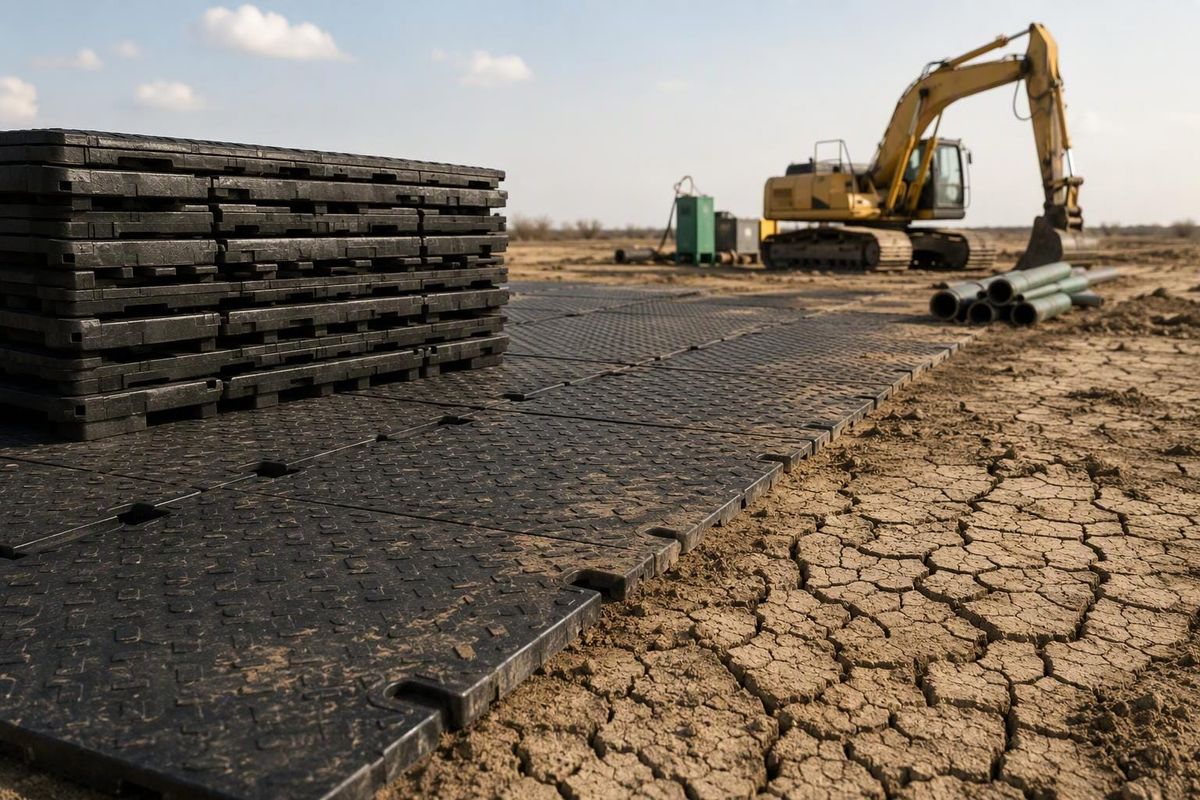
NPK International, which makes, sells and rents recyclable composite mats for worksite access, lowered its full-year guidance after exceptionally dry Texas weather cut matting demand, even as third-quarter revenue rose 11% to $76.3 million, the company reported Thursday.
Weather Hit Rentals, Not The Margin
Adjusted EBITDA, the company's preferred earnings measure before interest, taxes, depreciation and amortization, rose 30% to $20.0 million. The adjusted margin widened by 390 basis points to 26.2%.
GAAP measures were softer. Operating margin slipped to 12.0% from 13.2%, and income from continuing operations was $6.3 million, or $0.07 per diluted share, the same per-share figure as a year earlier. Third-quarter adjusted income was $7.9 million, or $0.09 per share.
The dry spell led several large utility projects to start without matting, the company said, and the Texas shortfall was partly offset by growth in other expansion markets. Rental and service revenue rose 12% to $49.6 million, while product sales rose 9% to $26.7 million.
Selling and administrative costs included about $1.2 million of severance tied to an executive leadership transition and $0.7 million of strategic planning and diligence costs.
Cash Flow Turns Negative
Operating cash flow fell to $7.1 million from $24.7 million a year earlier. Free cash flow was negative $4.4 million, against positive $12.5 million.
For 2026, NPK now expects revenue of $300 million to $305 million, adjusted EBITDA of $90 million to $93 million and capital spending of $70 million to $75 million. The spending range includes $40 million to $45 million for the rental fleet and about $20 million for the manufacturing expansion.
CEO Matthew Lanigan said rental project activity "significantly strengthened throughout October" and that growth expectations for 2027 are unchanged.
Louisiana Expansion And Buybacks
NPK is expanding its Carencro, Louisiana, manufacturing capacity by about 50%. The company expects to invest $40 million to $45 million by mid-2027, with $10.5 million spent through September 30, and production due to start by mid-2027.
Quoting activity has run at least 20% above last year throughout 2026, the company said, which it ties to its expectation of double-digit rental growth.
In the third quarter NPK spent $13.4 million to buy back 1.0 million shares, leaving $76 million under its authorization. It ended September with $26.3 million of debt, $4.2 million of cash and $132.2 million available under its credit facility.
Management discusses the results on a call Friday at 9:30 a.m. ET.
Sources
- 8-K Filing — NPK International Inc. (NPKI) — SEC EDGAR
- Exhibit a2026q38k-erex991.htm — NPK International Inc. 8-K exhibit — SEC EDGAR
- NPK Reports Third Quarter 2026 Results — businesswire.com