Teledyne Chairman Expects Varex Sales To Dip First, Then Margins To Rise
Robert Mehrabian said an 80-20 cleanup of smaller customers will trim Varex revenue early, before mid-single-digit growth returns.
Teledyne Executive Chairman Robert Mehrabian said on the company's third-quarter earnings call that the pending Varex purchase is mainly a margin play, with revenue likely "down a little bit" at the start. The call followed a quarter in which Teledyne raised its full-year outlook for the third time.
What Mehrabian said about Varex
Asked by an analyst how Teledyne would stimulate growth at a business with flat revenue, Mehrabian said the company will first apply its 80-20 principles. Detailed analysis has not been done yet, he said, because the deal is still going through its process.
The approach focuses on the 80% of revenue where margins can improve. The other 20%, he said, comes from smaller customers that are "diluted to earnings." He noted Teledyne has cut its own product SKUs by 50% over four or five years.
His sequence: revenue down a little at the start, gross margins up "almost first year," then mid-single-digit growth, as with Teledyne's other acquisitions. He also said Varex will not run separately. It will follow the "one Teledyne" sales approach, so one salesperson can see all of the company's products.
Mehrabian pointed to past deals as the template. Teledyne bought Clear at 16.7 times EBITDA, a measure of operating earnings, and he said that is down to 13.7 after four years. Across acquisitions, he said, the average was 13.5 times and is now under eight.
Why Varex, and the buyback
Mehrabian said Teledyne followed Varex for more than six years and approached it as healthcare markets recovered after the post-COVID period. Other bidders were in the process, he said, and that is detailed in Varex's merger proxy. The result was a friendly deal.
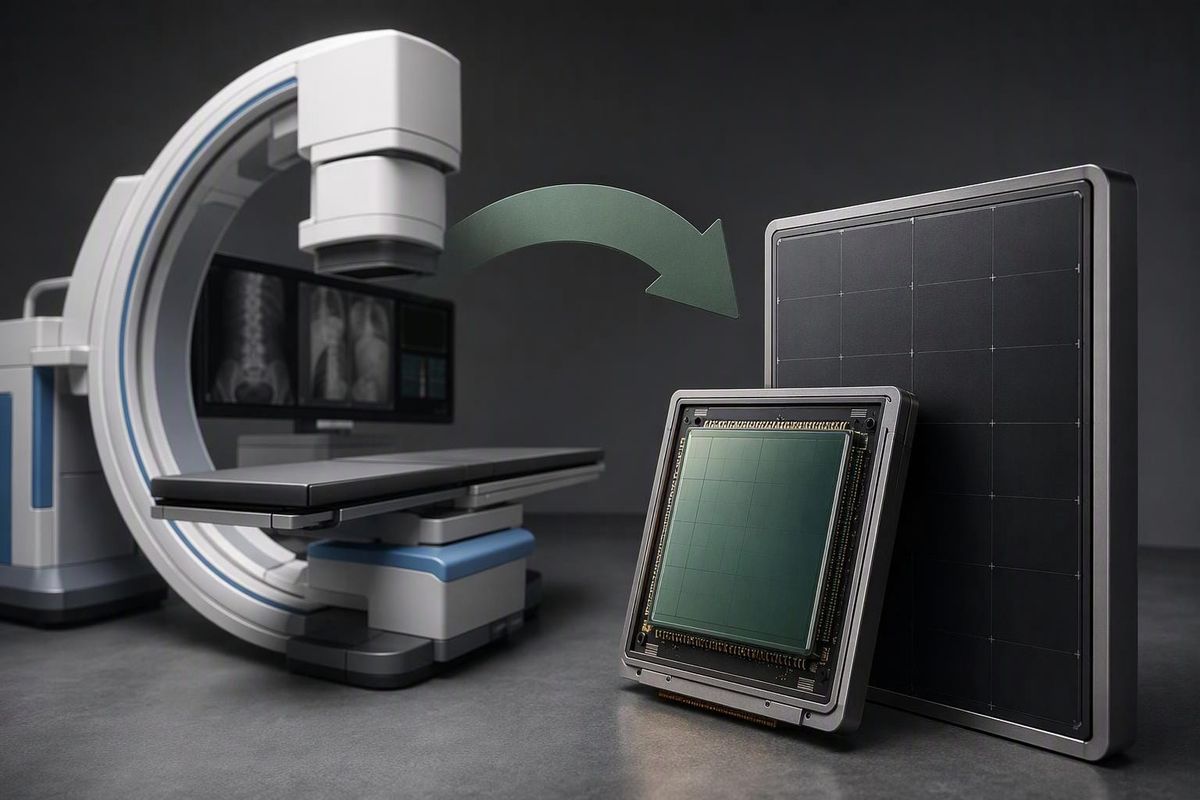
What excites him most, he said, is Varex's photon detectors, which sense X-rays without an intermediate scintillation layer. Teledyne's own X-ray detectors, he said, are ceramic metal oxide types that cannot handle the high energies used in oncology, while Varex's amorphous silicon detectors are built for them.
Separately, Mehrabian said Teledyne recently made $224.6 million of opportunistic share repurchases at a weighted average price of about $607 per share. He said leverage remains at its lowest level in six years despite the buyback and the pending deal.
On the quarter, he said sales and operating earnings were the strongest in Teledyne's history. The 2026 sales outlook is $6.625 billion, up 8.3% year over year, with adjusted earnings of $25.45 per share.
What to watch
Varex stockholders vote at a special meeting on October 28. Management said the regulatory process is underway and it still anticipates closing early in 2027.
Mehrabian's own summary of the Varex plan: revenue down a little at first, gross margins up, then growth like every other acquisition Teledyne has made.
Sources
- Teledyne Technologies Q3 Adj. EPS $6.72 Beats... — benzinga.com
- Teledyne Technologies Raises FY2026 Adj EPS G... — benzinga.com
- Teledyne Technologies (TDY) Surpasses Q3 Earnings and Revenue Estimates — Yahoo Finance
- Teledyne: Q3 Earnings Snapshot — Associated Press
- Teledyne Technologies Raises FY2026 GAAP EPS ... — benzinga.com