FormFactor Says 380 Basis Points Of Its 56.5% Gross Margin Won't Repeat
The CFO put the real gross margin baseline near 53% as the company ramps its new Texas factory in 2027.


FormFactor's third-quarter non-GAAP gross margin of 56.5% was padded by one-time items, CFO Eric McKinnis said on the company's earnings call Wednesday. About $10.5 million, or roughly 380 basis points, came mainly from tariff refunds and favorable quantum subcomponent costs that he does not expect to recur.
Strip out the one-timers, get 53%
Without those items, adjusted gross margin would have been between 52.5% and 53%, McKinnis said, about 150 basis points above the baseline management described last quarter. "We now view around 53% as the gross margin baseline at Q3 volumes," he said, crediting better labor performance, yields and manufacturing spending.
Tariff refunds alone were worth about 300 basis points, or $8.6 million, and about $0.09 of adjusted earnings per share. The company expects the remaining roughly $2 million in refunds in the fourth quarter, with no ongoing benefit after that.
Adjusted earnings were $1.04 per share, with revenue of $280.5 million, up 9% from the second quarter and close to 40% above a year earlier. Free cash flow was $64.8 million, up from $52.6 million in the second quarter. Cash and investments rose $50 million to $399 million.
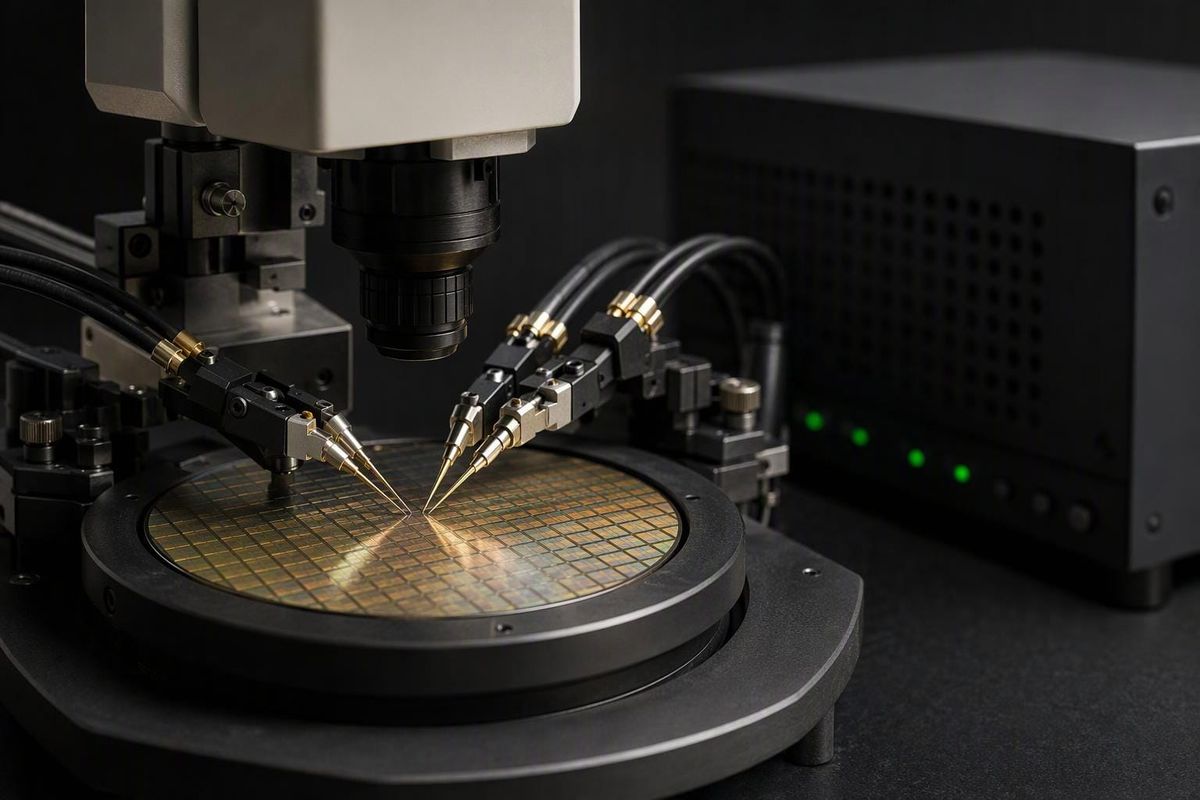
FormFactor makes the electrical and optical test equipment chipmakers use to check semiconductors, including probe cards and probe stations.
Texas ramp should not dent margins
A TD Cowen analyst asked why margins would not improve as volume grows in 2027. McKinnis said new-factory inefficiencies, such as added headcount, should be largely offset by higher volume and efficiency gains, so 2027 margins should stay near current levels.
Pressed by a Cantor Fitzgerald analyst to size the 2027 pluses and minuses, he said the company has not quantified them because it would be "a false sense of precision." He did say the Farmers Branch plant should add to margins once it reaches initial capacity.
By the end of 2027, the plant should be able to produce about $400 million in annual probe card revenue, McKinnis said, with the ramp roughly linear through the year. That is capacity, not revenue. CEO Mike Slessor called the ramp the company's top priority and said the first production unit shipped to a leading customer days ago.
Fourth-quarter outlook and a $1 billion year
For the fourth quarter, FormFactor guided to revenue of about $285 million, plus or minus $10 million, with gross margin of 54%, plus or minus 150 basis points, at the midpoint. Adjusted earnings are guided to 95 cents, plus or minus 9 cents.
Slessor said the midpoint puts the company on track to pass $1 billion of revenue in 2026. Triton photonic systems revenue is now expected to exceed $30 million this year, against an initial forecast of $10 million to $20 million. The company also cut its 2026 cash spending estimate for Farmers Branch to $100 million to $110 million from $140 million to $170 million, which McKinnis said is a timing shift into 2027.
Management's longer-term target model is $1.6 billion in revenue at 55% gross margin and $5 of adjusted earnings per share.
Sources
- FormFactor (NASDAQ:FORM) Q3: strong sales but stock drops 10.5% — Yahoo Finance
- FormFactor Stock Before Q3 Earnings: Smart Buy or Risky Move? — Yahoo Finance
- FormFactor sinks despite offering up strong Q3 results, guidance (FORM:NASDAQ) | Seeking Alpha — seekingalpha.com
- FormFactor: Q3 Earnings Snapshot — Associated Press
- FormFactor (FORM) Opens Texas Facility, But Is The Valuation Story Still Compelling — Yahoo Finance