Flex Projects Axiom Sales Of $20–$21 Billion In 2027, Versus $9.7 Billion This Year
The planned spin-off counts 95% of its 2027 revenue outlook as secured and plans about $2 billion in capacity investment.


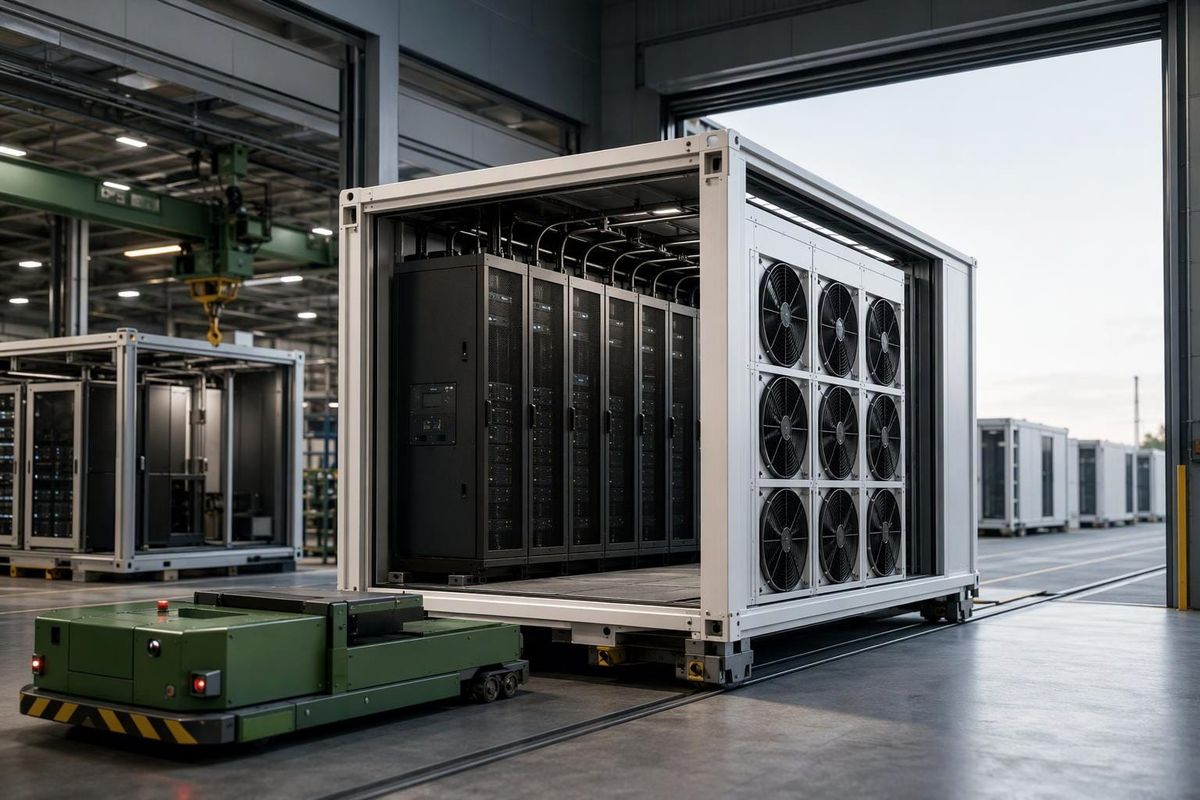
Flex, which designs and manufactures products for other companies, projected $20–$21 billion in calendar 2027 sales for its planned data-center infrastructure spin-off Axiom, versus approximately $9.7 billion estimated for 2026, in presentation materials furnished with Tuesday's SEC filing. Axiom counts 95% of that 2027 outlook as secured through backlog and customer commitments, including programs with customer co-investment.
Customer Programs Meet A Capacity Build-Out
Axiom plans approximately $2 billion in capital spending across 2026 and 2027, including a roughly 50% expansion of its modular manufacturing footprint. Its existing manufacturing network spans 19 sites and about 11 million square feet.
The business combines power equipment, computing systems, cooling and services. Axiom integrates and tests systems in factories before deployment; it estimates that factory-built modules can bring capacity online up to 50% faster than construction and integration at the customer site.
Cloud and cooling account for the larger sales outlook: Axiom expects $14–$14.7 billion in 2027, against about $6.2 billion estimated for 2026. It projects power sales of $6–$6.3 billion, versus approximately $3.5 billion this year.
Axiom expects its adjusted earnings margin before interest, taxes, depreciation and amortization to reach about 13%–14% in 2027, from approximately 11% estimated for 2026. The 2027 margin includes standalone corporate costs equal to about 1.25% of revenue.
Power Carries The Longer-Term Margin Bet
Axiom's 2030 framework targets sales above $37 billion and annual revenue growth exceeding 20% from 2027 through 2030. It expects power revenue to grow more than 40% annually over that period, compared with more than 10% for cloud and cooling.
The company expects power to supply about two-thirds of total adjusted earnings before interest, taxes, depreciation and amortization by 2030. Its consolidated margin target is close to 20%, supported by a larger contribution from power, pricing, productivity and operating leverage.
The spending burden is expected to ease as capacity comes online. Axiom projects capital spending at approximately 6% of revenue in 2027, versus about 10% in 2026, and about 3%–4% in 2030. It targets free cash flow equivalent to more than 40% of adjusted net income in 2027 and more than 90% in 2030, against negative conversion estimated for 2026.
Flex Keeps Manufacturing And A Debt Plan
Flex's remaining regulated manufacturing and integrated technology businesses generated $21 billion in fiscal 2026 sales. They serve healthcare, industrial, automotive, communications and lifestyle customers.
From 2019 through 2026, Flex exited structurally lower-margin operations, spun off Nextracker and built the power, computing and cooling business slated to become Axiom. Total Flex adjusted operating income rose from $0.9 billion in fiscal 2019 to $1.8 billion in fiscal 2026.
For the remaining business, Flex targets an adjusted operating margin of at least 7% in fiscal 2029, compared with a fiscal 2027 outlook of 5.7%–5.9%. It aims to increase higher-value markets from 24% of fiscal 2026 sales to 35%–40% in fiscal 2029. Those markets include medical devices, drug delivery, energy infrastructure, robotics, advanced networking and satellite communications; the fiscal 2029 figures are direction, not guidance.
Flex expects approximately $5.2 billion in debt after separation. It plans to retain roughly 10%–12% of Axiom and exchange that stake for Flex debt within 24 months, projecting approximately $100 million in annual interest savings.
Flex said the planned Axiom separation remains on track for the first quarter of calendar 2027.
Sources
- 8-K Filing — FLEX LTD. (FLEX) — SEC EDGAR
- Exhibit d150156dex991.htm — FLEX LTD. 8-K exhibit — SEC EDGAR
- Exhibit d150156dex992.htm — FLEX LTD. 8-K exhibit — SEC EDGAR