10x Genomics Says Factory And Install Capacity, Not Orders, Will Cap Atera At About 50 A Quarter
The CEO said building and installing the new instrument is the limit, and the CFO warned fourth-quarter gross margin falls from 75%.


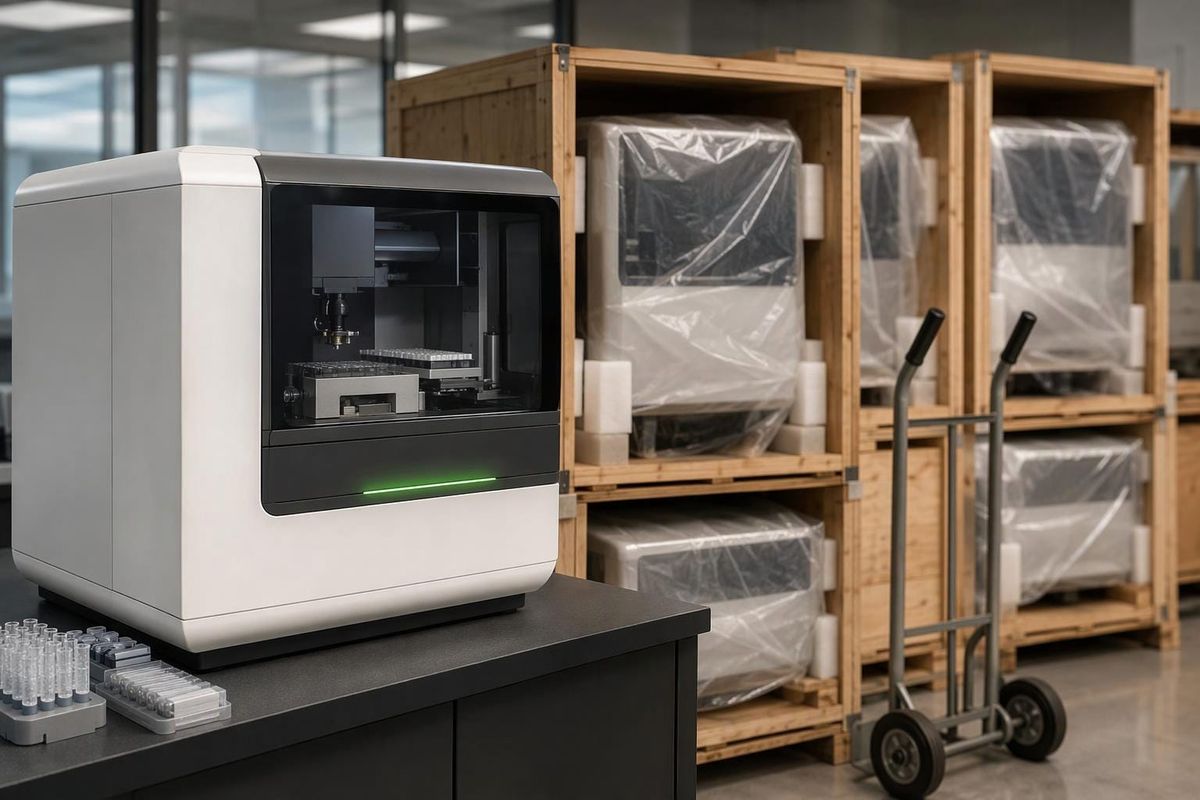
10x Genomics, which makes instruments and consumables for studying single cells and tissue, will be held back by production and installation capacity rather than demand for its new Atera instrument, CEO Serge Saxonov said on the company's third-quarter earnings call Thursday. The company now expects to ship about 50 Atera units by the end of this year, up from about 40.
Orders aren't the problem
Asked about backlog, Saxonov said the company does not share order numbers. He added that with Atera "the binding constraint here is not orders at all," but rather scaling up manufacturing and the capacity to install and train customers. He said that will hold next quarter and into next year.
An analyst from Canaccord Genuity asked whether 40 to 50 placements a quarter was the right way to think about next year's ramp. Saxonov said "demand is not the bottleneck" and that thinking about "50 a quarter" given those constraints is "about the right number." Customer success, he said, is the company's "North Star."
He said more than 100 customers booked projects in the first five months of Catalyst Research Services, the company's internal service lab for running customer samples. Nearly all of the world's top 20 biopharma companies have bought Atera systems or services through Catalyst, he said.
Margins step down from 75%
CFO Adam Taich said gross margin was 75% in the third quarter, up from 67% a year earlier on lower inventory write-downs and product mix. He expects the fourth quarter in the low to mid 60s as Atera shipments ramp.
For 2027, Taich said margins will most likely come in lower, because it will be an instrument-heavy year with consumables ramping during it. He said Atera's overall margin profile is higher than Xenium's, for both instruments and consumables, and that guidance will come early next year.
Taich raised the 2026 revenue outlook to $625 million to $635 million, from $610 million to $630 million. Excluding patent-litigation settlement revenue in both years, he said that is 4% to 6% growth over 2025.
A quarter of waiting buyers
Third-quarter revenue was $150.7 million, up 1% from a year earlier. Spatial instrument revenue fell 57% as customers moderated purchases of Visium and Xenium ahead of Atera, Taich said, and total instrument revenue fell 43%. Only a couple of Atera units were in the quarter's revenue.
Spatial consumables revenue rose 16%, and Taich said it should stay in double digits in the fourth quarter. The company ended the quarter with $576 million in cash, cash equivalents and marketable securities. Atera was announced in April and began shipping in late September.
Taich said the company will give 2027 guidance early next year, including how margins hold as Atera placements and consumables ramp.
Sources
- 10x Genomics forecasts $625M-$635M 2026 revenue as it targets ~50 Atera shipments by year-end (NASDAQ:TXG) | Seeking Alpha — seekingalpha.com
- 10x Genomics: Q3 Earnings Snapshot | wusa9.com — Associated Press
- 10x Genomics (TXG) Reports Q3 Loss, Beats Revenue Estimates — Yahoo Finance
- Compared to Estimates, 10x Genomics (TXG) Q3 Earnings: A Look at Key Metrics — Yahoo Finance
- Sentira AI Launch Puts 10x Genomics Stock In Focus Before Earnings — Yahoo Finance